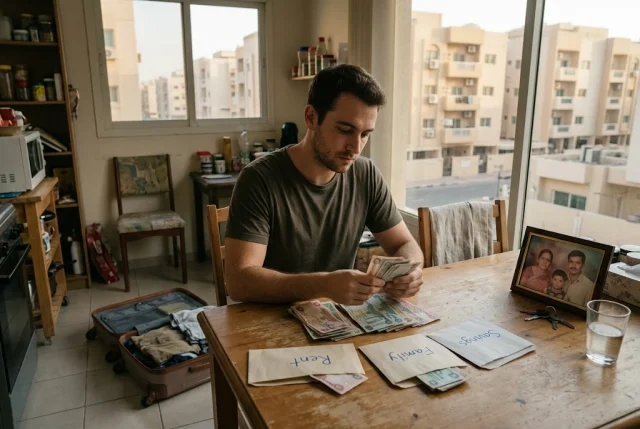
Living in the United Arab Emirates can offer exciting opportunities, but managing money abroad is not always easy.
Between rent, groceries, transport and supporting family back home, your salary may disappear faster than expected.
Understanding how to move out of survival mode financially while living abroad begins with changing how you organise your income and expenses.
Financial survival mode happens when you constantly worry about covering basic costs, struggle to save and depend on your next salary to meet immediate needs.
Fortunately, small financial adjustments can help you regain control. You do not need to earn a huge salary to start improving your situation.
What does financial survival mode look like in the UAE?
Financial survival mode means spending most or all of your income on immediate needs, with little money remaining for savings or unexpected expenses.
For expatriates living in Dubai, Abu Dhabi or Sharjah, this situation can develop when living costs and financial responsibilities become difficult to balance.
Some common signs include:
- Running out of money before your next payday.
- Using credit cards to pay for groceries or essential bills.
- Having no emergency savings.
- Sending money home without calculating what you can afford.
- Feeling anxious about rent, transport or monthly payments.
- Postponing financial goals because your income is already committed.
These situations can create a cycle where you work primarily to cover expenses rather than build financial security.
The challenge is that even a salary increase may not solve the problem if spending grows at the same pace.
That is why understanding your financial habits is just as important as increasing your income.
How to move out of financial survival mode while living abroad
The first step towards financial stability is understanding exactly where your money goes.
Instead of making dramatic lifestyle changes, focus on building a realistic system that works with your income.
Understand your actual monthly expenses
Start by reviewing your bank statements from the previous month.
Separate essential expenses, such as accommodation, utilities and groceries, from optional purchases.
For example, imagine an expatriate earning AED 7,000 per month.
Their monthly expenses might include:
- Accommodation: AED 2,500.
- Groceries: AED 800.
- Transport: AED 500.
- Utilities and phone: AED 400.
- Family support abroad: AED 1,000.
- Personal spending: AED 800.
In this illustrative situation, total spending reaches AED 6,000, leaving AED 1,000 available.
That remaining amount could be divided between emergency savings and future financial goals.
The purpose of this exercise is not to follow someone else’s budget. It is to understand your own financial reality.
Reduce spending without sacrificing everything
Living abroad can come with pressure to enjoy restaurants, shopping centres and entertainment.
However, spending money on experiences should not prevent you from covering essential needs.
Look for expenses that can be reduced without affecting your quality of life significantly.
You might prepare more meals at home, review unused subscriptions or compare transport options.
Even reducing unnecessary spending by AED 300 monthly creates AED 3,600 in potential annual savings.
Small changes become meaningful when maintained consistently.
Create a budget that includes savings
A budget is simply a plan showing how your income will be used.
Start by allocating money to essential expenses and existing financial commitments.
Then decide how much you can realistically save.
Avoid setting an unrealistic savings target that forces you to borrow money before payday.
Instead, begin with a manageable amount and increase it when your financial situation improves.
Manage financial responsibilities across two countries
One of the biggest challenges of living abroad is managing financial commitments in more than one country.
Many UAE residents support relatives overseas while paying their own living expenses locally.
This can make financial planning more complicated.
Set a realistic limit for international transfers
Sending money to family may be an important responsibility, but transfers should fit within your monthly budget.
Decide how much you can send without compromising essential expenses or relying on credit.
For example, if your monthly income is AED 8,000, you might allocate AED 1,000 towards family support, depending on your circumstances.
Before transferring money, compare exchange rates and transaction fees.
The Central Bank of the UAE regulates licensed financial institutions, including relevant payment and exchange services. Choosing an appropriately licensed provider can help you make safer financial decisions.
Prepare for unexpected expenses abroad
Unexpected costs can be particularly stressful when living outside your home country.
Emergency travel, medical expenses not covered by insurance or employment changes may require immediate access to money.
An emergency fund helps you manage these situations without automatically depending on loans.
Start with a small target, such as AED 1,000, and gradually increase your savings.
Over time, consider building enough savings to cover several months of essential expenses.
Your ideal emergency fund will depend on your employment stability, family responsibilities and financial commitments.
Plan for expenses that happen occasionally
Not every financial responsibility appears monthly.
Annual travel, insurance renewals, visa-related expenses and family visits can affect your budget.
Instead of treating these costs as surprises, estimate them in advance.
If you expect to spend AED 2,400 on travel during the year, saving AED 200 monthly can help you prepare.
This approach makes irregular expenses easier to manage.
Build habits that create long-term financial stability
Escaping financial survival mode requires more than reducing spending for a few weeks.
The goal is to develop habits that make your finances more predictable.
Save money when your salary arrives
Waiting until the end of the month to save can be difficult because unexpected purchases may consume the remaining balance.
Consider transferring a small amount into a separate savings account when you receive your salary.
Some UAE banks offer digital savings and scheduled transfer features.
Before opening an account, check minimum balance requirements, applicable fees and other conditions.
These details matter because some accounts may charge fees when certain requirements are not met. The Central Bank’s consumer protection standards require licensed institutions to disclose relevant account conditions.
Avoid using credit to maintain your lifestyle
Credit cards can be useful financial tools, but relying on borrowed money for everyday expenses may create additional pressure.
If you cannot repay your full balance, interest or other financing charges may apply depending on your agreement.
Review your outstanding debts and identify which balances are costing you the most.
If repayments become difficult, contact your financial institution to discuss available assistance.
UAE consumer protection rules require licensed financial institutions to assess affordability and provide appropriate support for borrowers experiencing repayment difficulties.
Review your progress every month
Financial stability develops through consistent decisions.
At the end of each month, review your expenses, savings and outstanding debts.
Identify what worked and what needs improvement.
You may discover that certain spending categories are consistently higher than expected.
Use this information to adjust your budget rather than abandoning it.
Over time, these reviews can help you make more confident financial decisions.
Turn financial pressure into a more secure future
Learning how to move out of survival mode financially while living abroad is not about becoming wealthy overnight.
It is about reaching a point where your income supports your daily needs while allowing you to prepare for the future.
For UAE expatriates, this means balancing local living expenses, family responsibilities, savings and financial goals.
Start by reviewing your spending, setting realistic limits and building a small emergency fund.
You do not need to change everything immediately. One sustainable improvement can be the beginning of a more stable financial future.
Frequently asked questions
How can expatriates save money while living in the UAE?
Expatriates can begin saving by tracking monthly expenses, reducing unnecessary purchases and setting realistic financial priorities.
Comparing accommodation costs, transport options and grocery expenses may help identify opportunities to save.
Creating a separate savings account and transferring a manageable amount each month can also support long-term financial stability.
How much money should I save every month in the UAE?
There is no universal amount that works for everyone. Your savings target should depend on your salary, essential expenses, existing debts and family responsibilities.
Start with an amount you can consistently afford, even if it is AED 100 or AED 200 monthly. Increase your contributions when your financial circumstances improve.
Is it possible to escape financial survival mode on a low salary?
Yes, although progress may be slower when income is limited. Begin by identifying essential expenses, reducing avoidable costs and avoiding unnecessary borrowing.
Building a small emergency fund can help protect against unexpected bills. If your income does not cover basic needs, improving your earnings or reducing major fixed expenses may also be necessary.
How long does it take to become financially stable while living abroad?
The timeline depends on your income, expenses, debts and personal responsibilities. Some people may notice improvements after several months of consistent budgeting, while others need more time.
Focus on measurable progress, such as reducing debt, saving regularly and covering monthly expenses without borrowing.
Financial stability is a gradual process rather than a fixed deadline.